
The most reliable approach for institutional prepayment risk modeling is a calibrated hazard model that pairs an economic refinance incentive feature with a stable baseline, typically regularized logistic regression or Cox proportional hazards, built on strict no-leakage loan-month data. Start there: construct a clean risk set, run a calendar-time backtest, and only add complexity (boosting, neural networks, multi-factor rate models) once the baseline's calibration and stress performance are documented and defensible to examiners.
TL;DR:
- Static models may be sufficient for small, low-rate-sensitive portfolios, but portfolios with significant refinance exposure need dynamic, incentive-based models.
- Logistic regression and Cox hazard models remain the most transparent and defensible baseline, especially when built on carefully no-leakage, monthly loan data.
- Incorporating rate-driven, scenario-capable frameworks becomes essential for portfolios with embedded options or when performing Monte Carlo stress testing.
- Calibration and validation should rely on calendar-time splits, with specific focus on probability calibration and economic impact through cash-flow errors.
- Automating model governance and backtesting processes with a platform like Riskinmind reduces operational burden and ensures ongoing compliance and validation.
Automate Regulatory Model Risk Governance
Examine models against 32 qualitative criteria and resolve risk Tiers with pre-deployment checklists per OCC 2011-12 guidelines.
Table of Contents
- Prepayment Modeling Approaches: Static vs. Dynamic Frameworks
- Statistical and Machine Learning Techniques for Prepayment Modeling
- Feature Engineering, Leakage Controls, and Competing Risks
- Calibration, Backtesting, and Model Governance
- From Probabilities to Portfolio Metrics: CPR, SMM, Duration, and Convexity
- Implementation Notes: Engineering the Model Pipeline
- How Automated Platforms Support Model Governance at Scale
- When Simple Wins and When Complexity Pays Off
- Put Prepayment Governance on Autopilot with Riskinmind
- Sources
- FAQ
Prepayment Modeling Approaches: Static vs. Dynamic Frameworks
Static CPR and PSA-ramp models still show up in ALCO decks for a reason: they are transparent, cheap to run, and easy to explain to a board that does not want a lecture on hazard functions. A static model assigns a single conditional prepayment rate, or a ramp toward one, to a cohort based on loan age. Regulators tolerate this for smaller portfolios or non-material exposures because the assumption is auditable in a single sentence. The Comptroller's Handbook on interest rate risk treats the prepayment option as a material embedded option regardless of model choice, which means even a static assumption needs documentation and periodic testing against realized behavior.
Dynamic models earn their complexity when refinance incentive actually moves the portfolio. These frameworks let prepayment speed respond to the gap between a borrower's note rate and current market rates, to seasoning effects that ramp speeds up through year three, and to burnout, the well-documented pattern where a pool that has already been picked over by refinancers slows down even when rates make refinancing attractive again. Seasonality adds a smaller but real signal, since home sales and relocations cluster in spring and summer.
Hazard and survival approaches, whether continuous-time or discrete-time, solve a problem static and even most dynamic regression models handle poorly: censoring. A loan that has not prepaid by the end of your observation window is not a "no," it is unresolved, and treating it as a clean negative label biases every downstream estimate. Discrete-time hazard models, built on loan-month panels, are the workhorse in practice because they map cleanly onto the monthly cadence of MBS reporting.
Reduced-form, rate-driven frameworks add macroeconomic structure on top. A two-factor Hull-White model, for instance, lets short and long rate factors evolve stochastically and drives prepayment speed off simulated rate paths rather than a single deterministic incentive figure, which MathWorks demonstrates in a widely referenced implementation. This matters most for institutions running Monte Carlo scenario analysis or valuing MBS with embedded optionality, where a single rate path badly understates the range of plausible prepayment outcomes.
Choosing among these families comes down to portfolio materiality:
- Small, homogeneous portfolios with low rate sensitivity can often defend a static CPR/PSA assumption, provided it is back-tested.
- Portfolios with meaningful refinance exposure need dynamic incentive features at minimum.
- Investors and originators managing convexity risk on MBS books need rate-driven, scenario-capable frameworks.
- Any portfolio with material embedded prepayment options needs documented stress testing regardless of model family, per OCC expectations.
Statistical and Machine Learning Techniques for Prepayment Modeling
Start with the boring model. Regularized logistic regression, applied to loan-month data with an incentive feature, seasoning, and a handful of borrower covariates, remains the most defensible baseline in prepayment modeling techniques because every coefficient has a sign an examiner can sanity-check. If refinance incentive carries a negative coefficient on prepayment hazard, something in your data pipeline is broken. That interpretability is not a consolation prize; it is often the deciding factor in whether independent model validation clears the model in weeks or quarters.
Cox proportional hazards and its discrete-time cousin extend that same auditability to time-to-event data. The discrete-time hazard formulation, where each loan-month becomes an observation with a binary "prepaid this month" outcome, is the format most reproducible modeling work is built around. A public example using Freddie Mac loan-level data structures the problem exactly this way, with calendar-time splits and calibration checks built into the workflow rather than bolted on afterward.
Gradient boosting machines and neural networks add real lift when the underlying relationships are nonlinear, which refinance incentive often is. The relationship between rate gap and prepayment speed is not a straight line. It curves sharply near the point where refinancing costs stop being worth it, then flattens at extreme incentive levels as capacity constraints and underwriting friction cap the response. Tree-based boosting captures that curvature better than a plain logistic specification. The tradeoff is calibration drift: high-capacity models often nail discrimination while producing probability estimates that are systematically off in specific score bands, which is exactly what post-hoc calibration exists to fix.
Pro Tip: Run a calibration curve by decile of predicted hazard before you trust any boosted model's aggregate CPR output. A model with excellent ROC AUC can still overstate prepayment risk in the top decile by a wide margin if nobody checks the curve.
A defensible evaluation stack combines several angles rather than one headline number:
- ROC AUC for overall discrimination between prepayers and non-prepayers.
- PR AUC for retrieval quality on prepayment as the minority event in most loan-months.
- Brier score and calibration-by-score-band for probability quality.
- UPB-weighted CPR error, which converts probability errors into dollar-weighted cash-flow impact.
A useful validation set combines discrimination, minority-event retrieval, probability quality, calibration by score band and month, and UPB-weighted CPR or SMM error, prioritizing calibration and economic impact over raw classification accuracy alone. That framing, more than any single algorithm choice, separates models that survive independent validation from ones that get sent back for rework.
Feature Engineering, Leakage Controls, and Competing Risks
Your feature set determines how much of the prepayment story your model can actually tell, and most of the useful signal comes from a short list of variables. Refinance incentive, calculated as the borrower's note rate minus a comparable current market rate, drives the bulk of rate-sensitive prepayment behavior. Age and seasoning capture the well-known prepayment ramp. Prior months spent in-the-money captures burnout, since a loan that has spent many months with a strong incentive to refinance and hasn't moved is less likely to move now. LTV, FICO, occupancy type, and origination channel round out the borrower and loan covariates that explain why two loans with identical incentive can behave differently.
Building these features without leaking information from the future takes discipline:
- Construct the risk set so every loan-month observation only uses information available through month t minus one, never data from the outcome month itself.
- Lag every time-varying feature, including market rate benchmarks, by at least one reporting cycle to match real-world data availability.
- Model competing risks separately: refinance, home sale, and default are mutually exclusive outcomes, and collapsing them into a single "terminated" label biases hazard estimates for each individual path.
- Aggregate competing hazards through a multinomial or competing-risk-forest structure rather than treating each as an independent binary classification problem run in isolation.
- Weight training and evaluation by unpaid principal balance, since a $500,000 loan prepaying matters more to cash flow than a $40,000 loan doing the same.
- Document your imputation strategy for missing FICO or LTV values explicitly, since silent imputation is one of the most common sources of validation findings.
Calibration, Backtesting, and Model Governance
Random train/test splits are the fastest way to fool yourself about prepayment model performance. Loan behavior in 2021's refinance wave looks nothing like behavior in a rate-hike environment, so a random split lets the model peek at both regimes during training and inflates apparent accuracy. Calendar-time splits, training on one period and validating on a later, unseen period, along with rolling-origin folds that walk forward through time, are the standard practitioners increasingly favor precisely because they detect regime shifts that random splits miss. Vintage holdouts, where entire origination years are excluded from training, add a second layer of robustness by testing whether the model generalizes across underwriting eras rather than memorizing one.
Translating probability errors into economic terms is what makes a validation report useful to ALCO rather than just to modelers. A model that is off by two percentage points of hazard probability sounds small until you convert it into CPR error and multiply by the UPB of the affected cohort; that conversion is what turns a statistics problem into a cash-flow mismatch examiners actually care about.

Calibration technique matters here. Platt scaling works well for roughly sigmoid miscalibration patterns, while isotonic regression handles more irregular calibration curves at the cost of needing more data per bin. Either way, recalibrate on a fixed cadence rather than waiting for a validation cycle to surface drift.
A defensible governance package includes:
- Stress testing across a full range of rate shocks, from negative 200 to positive 400 basis points, plus nonstandard scenarios like rapid rate reversals.
- Independent model validation separate from the model-building team, consistent with OCC interagency guidance on interest rate risk practices.
- Written assumption documentation covering data vintage, feature definitions, and known limitations.
- A recalibration schedule tied to a monitoring trigger, not just a calendar date.
From Probabilities to Portfolio Metrics: CPR, SMM, Duration, and Convexity
A hazard model's output is a monthly conditional probability, and that number is useless to a treasury desk until it becomes SMM, then CPR, then a full cash-flow schedule. The SIFMA standard formulas define this chain precisely: the single monthly mortality rate converts to the conditional prepayment rate through the standard annualization formula, and CPR maps to PSA convention as a percentage of the 100% benchmark ramp.
Average life calculation requires UPB-weighted aggregation across the projected paydown schedule, not a simple average of loan maturities. Faster prepayment speeds shorten average life and shift duration lower, which sounds beneficial until you consider the direction: prepayments accelerate exactly when rates fall, meaning the bondholder gets principal back precisely when reinvestment options are worse. That asymmetry is negative convexity, the defining risk characteristic of mortgage-backed securities, and it is why prepayment risk modeling matters as much to portfolio-level interest rate risk analysis as it does to individual loan credit risk.
Practical reconciliation matters just as much as the math. Comparing your model's projected CPR against FHFA's published cohort-level three-month CPR figures gives you an external check that your internal assumptions haven't drifted from market reality. Build this into a routine checklist:
- Convert hazard output to SMM, then annualize to CPR using the standard formula.
- Map CPR to PSA convention for comparability with legacy assumption sets.
- Weight paydown projections by UPB before calculating average life.
- Reconcile quarterly against FHFA cohort benchmarks and flag deviations beyond a defined tolerance.
Implementation Notes: Engineering the Model Pipeline
Loan-month granularity generates enormous data volume fast: a 50,000-loan portfolio observed monthly over five years produces three million rows before you add a single feature. Storage and query design need to account for that scale from day one, not after the first slow backtest.
Refresh cadence matters more than most teams plan for. Market rate benchmarks should update at least weekly; servicing events like modifications or forbearance flags need near-real-time capture, since a stale servicing flag is a common source of quiet feature drift. Keep training and scoring pipelines physically separate so a scoring run never accidentally trains on data it should be evaluating, and maintain feature lineage documentation detailed enough that a model card can be regenerated without asking the original author.
Scenario scaling is where computational choices bite hardest. Monte Carlo rate-path simulations for convexity analysis need parallelized scoring infrastructure, since running thousands of rate paths sequentially against a large portfolio turns a business dashboard task, into an overnight batch job. The most common engineering failures are mundane: join-time leakage from mismatched timestamp keys, training windows too narrow to span a full rate cycle, and vintage data silently overwritten during a routine refresh.
How Automated Platforms Support Model Governance at Scale
Running this pipeline manually across a growing loan portfolio strains even well-staffed risk teams, and that operational burden is where a platform built for financial institutions earns its place. Riskinmind's architecture, coordinated by its central AI director Ava, is built to handle exactly the repeatable, audit-sensitive tasks that prepayment modeling generates: feature pipelines that respect no-leakage construction, calendarized backtesting jobs run on a fixed schedule, and UPB-weighted scenario aggregation across stress bands.
Specialized AI agents within the platform can support this workflow in a few concrete ways:
- Automated report generation for independent model validation handoffs, cutting documentation lag between build and review.
- Scenario sweeps across rate shock ranges without manual re-configuration for each run.
- Audit trail capture that logs assumption changes and recalibration events for examiner review.
Riskinmind's SOC 2® aligned controls and sub-second processing architecture matter specifically because prepayment governance depends on traceability, not just accuracy.
When Simple Wins and When Complexity Pays Off
Most institutions overbuild before they've earned the complexity. A defensible CPR/PSA assumption, back-tested and documented, beats an unvalidated hazard model every time an examiner walks in. Dynamic hazard pipelines pay off when refinance exposure is material, portfolio size supports statistical power, and someone owns ongoing recalibration.
Before building one, ask three things: Does incentive-driven behavior actually move your realized speeds? Can you staff independent validation on an ongoing basis? Will the economic-value gain from better calibration exceed the governance cost of running it?
— Raj
Put Prepayment Governance on Autopilot with Riskinmind
Building a defensible prepayment risk model is one project. Keeping it validated, documented, and stress-tested every quarter, across every cohort, indefinitely, is a different kind of workload entirely, and it's the one that quietly consumes risk teams. Riskinmind is built for that second problem: an in-house AI platform that automates the recurring, audit-heavy mechanics of model governance, backtesting jobs, scenario sweeps, documentation trails, so your quantitative staff spend time on judgment calls, not spreadsheet maintenance.
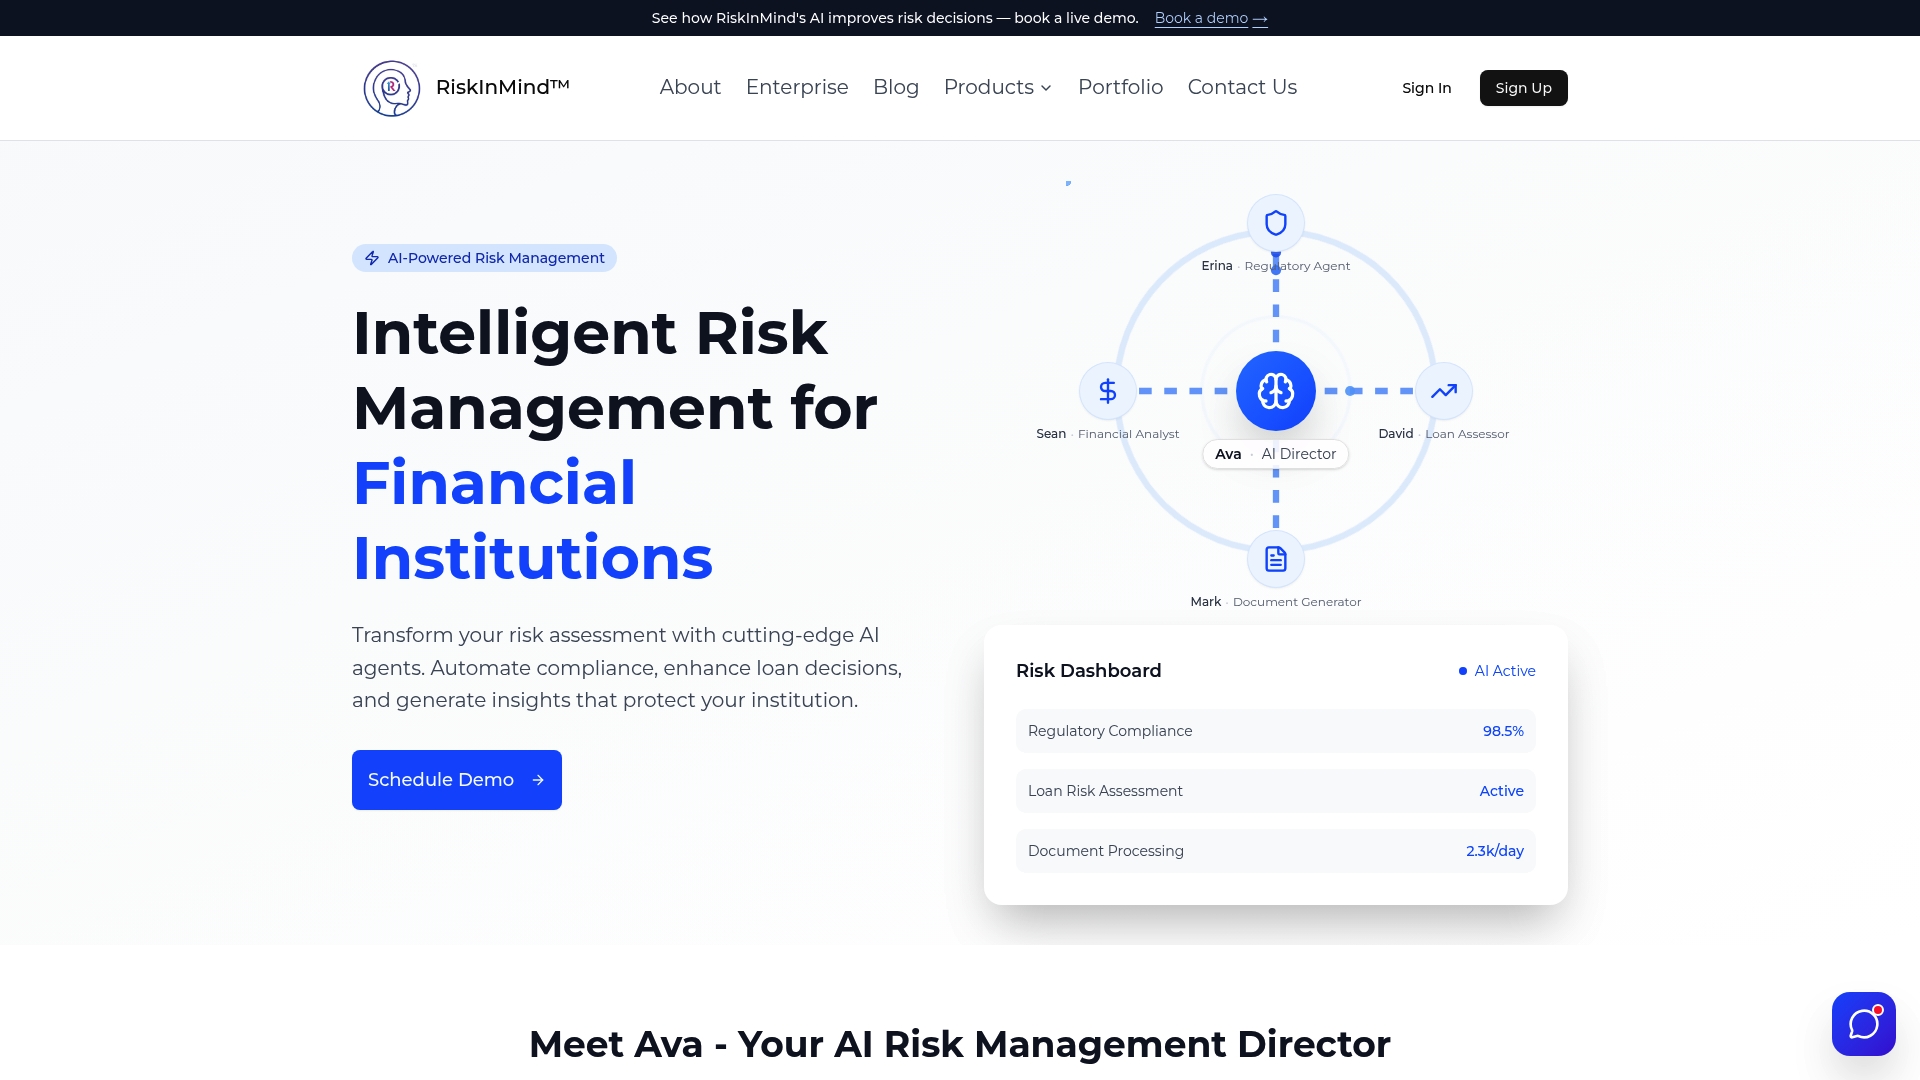
The platform's product suite covers portfolio monitoring, regulatory reporting, and credit risk assessment under one system with SOC 2® aligned controls and bank-grade security, built specifically for credit unions and community banks that can't afford a third-party data exposure. If your prepayment assumptions touch loan-level ingestion or underwriting workflows, the loan application product shows how that data connects upstream. Check current Starter, Professional, and Enterprise pricing and book a demo to see how much of your next validation cycle can run itself.
Sources
Practitioners building or validating a prepayment model should keep these primary sources close at hand. FHFA's Prepayment Monitoring Report publishes the cohort-level three-month CPR benchmarks used across the industry for reconciliation. The Comptroller's Handbook on Interest Rate Risk lays out regulatory expectations for documenting and stress-testing embedded prepayment options. SIFMA's standard formulas reference is the definitive source for SMM, CPR, and PSA conventions. For hands-on implementation patterns, a public Freddie Mac loan-level modeling repository demonstrates leak-free risk-set construction and calendar-time validation, while MathWorks' two-factor Hull-White example walks through rate-driven reduced-form modeling in detail.
- Prepayment Monitoring Report Second Quarter 2025 | FHFA
- Interest Rate Risk, Comptroller's Handbook
- Standard formulas for the analysis of mortgage-backed and other related securities
- Mortgage prepayment modeling with public Freddie Mac data
- Prepayment Modeling with Two Factor Hull White Model — MathWorks
FAQ
What Is Prepayment Risk?
Prepayment risk is the uncertainty that a borrower repays a loan earlier than scheduled, shortening cash flows and forcing reinvestment at potentially lower rates. It's the primary source of negative convexity in mortgage-backed securities, since prepayments accelerate when rates fall and slow when rates rise, the opposite of what a fixed-income holder wants.
What Is SATO in Mortgages?
SATO stands for spread at origination, the difference between a loan's note rate and the prevailing market rate at the time it was originated. It's used as a proxy for refinance incentive and borrower risk profile in many prepayment models, since loans originated with wide SATO often behave differently than loans priced closer to market.
Does a CMO Have Prepayment Risk?
Yes. A collateralized mortgage obligation redistributes prepayment risk across tranches rather than eliminating it, so some tranches absorb faster paydown risk while others are structured for more stable cash flows. The underlying mortgage collateral still carries the same embedded prepayment option described in OCC guidance.
How Do MBS Investors Make Money?
Mortgage-backed security investors earn income from the interest and principal payments passed through from underlying mortgage pools, priced to reflect expected prepayment speed. Accurate prepayment risk modeling directly affects the price an investor is willing to pay, since faster projected prepayments shorten expected cash flows and change the security's effective yield and duration.
How Does Riskinmind Support Prepayment Risk Modeling?
Riskinmind's platform automates the recurring operational work around prepayment risk modeling, including calendarized backtesting, audit trail documentation, and scenario aggregation, under SOC 2® aligned security controls. Current plan pricing for Starter, Professional, and Enterprise tiers is available on the Riskinmind pricing page.